Liza Shulman on the Institutional Shift: Turning Blockchain Capabilities into Scalable Partnerships
By Lauren Towner · 19 October 2026
Written by Matthew Kayser
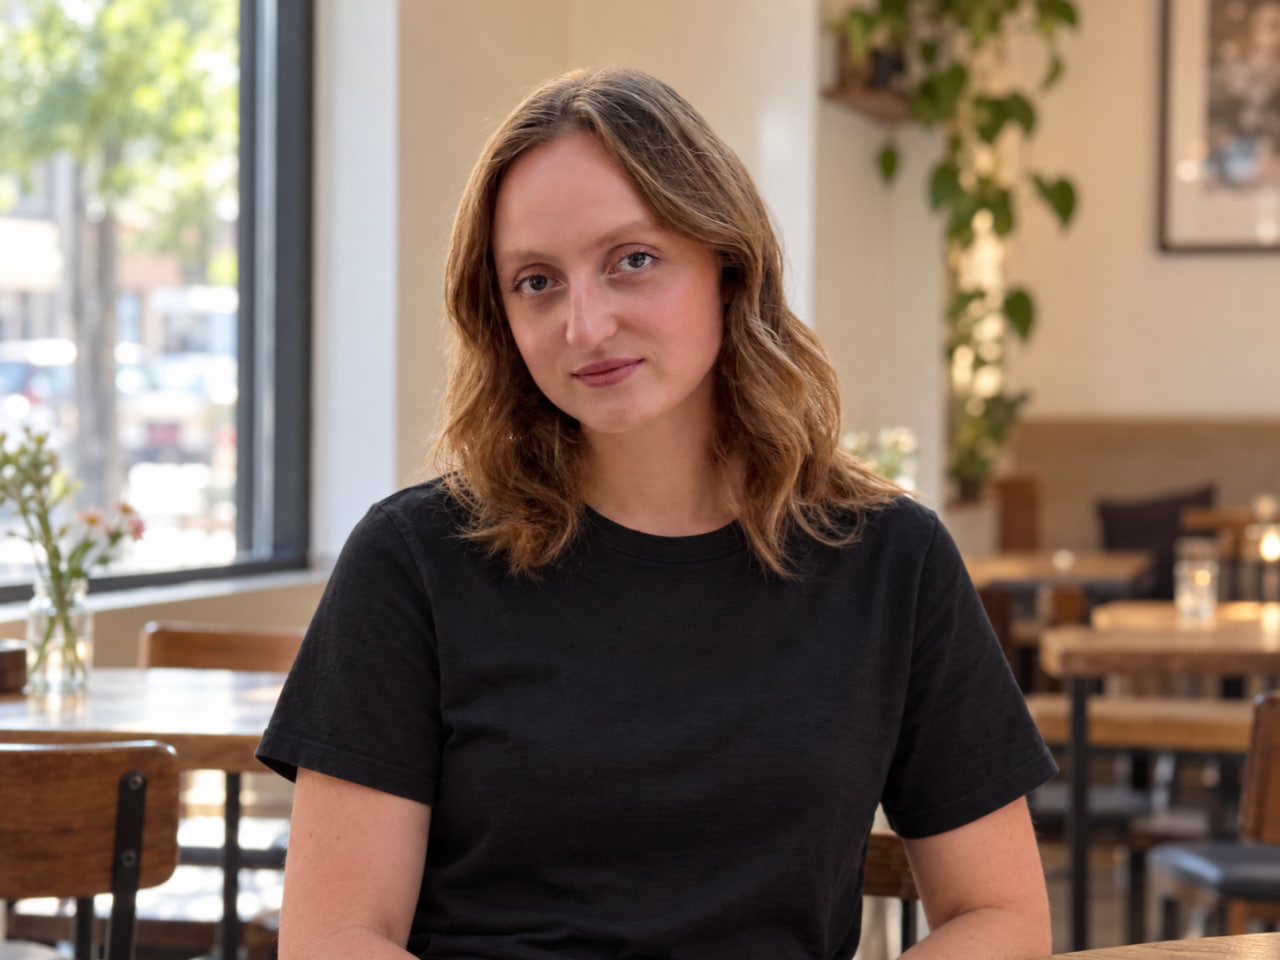
Blockchain's core capabilities, from programmable money to tokenized ownership, are proven. The next phase of adoption depends on institutions building them into their products. Liza Shulman, who has spent over six years in business development, partnerships, and account management, explains how to turn the technology's strengths into partnerships that institutions can approve and scale.
Blockchain has spent more than a decade proving what it can do. Value can move across borders in minutes rather than days, ownership can be represented and transferred as a token, and money itself can be programmed to follow rules. Early adopters understood this quickly, and they built much of today's industry.
The next wave of adoption looks different, and it is already well underway inside large institutions. J.P. Morgan's blockchain platform, Kinexys, processes more than $2 billion in transactions a day on average, and the bank has made its JPM Coin deposit token available to institutional clients on Base, a public blockchain network. Citi is working with Coinbase to make it easier for its institutional clients to use stablecoins in payments. BlackRock launched its first tokenized fund, BUIDL, on Ethereum, and consumer and luxury brands are looking for new ways to engage clients too. These institutions see the potential. What they need is a clear line from the technology's capabilities to their own economics, risk frameworks and decision-making.
Building that line has been at the center of Liza Shulman's career. Over six years in business development, partnerships and account management, she has managed relationships with hundreds of projects. Her experience includes the Abu Dhabi Investment Office, a government entity, where she gained a government perspective on the industry. She also worked at NFTrade, a multichain NFT marketplace, and on the investment side with launchpads and investor networks. At GoMining, a Bitcoin ecosystem company, she drove go-to-market collaborations with major companies, helping bring new technologies to early adopters. Her counterparts have ranged from protocol founders and investors to large enterprises and luxury brands. She has a computer science background and started out as the founder of an e-commerce business.
"The technology is genuinely powerful, and institutions increasingly know it," she says. "The question they're asking now is how it fits: into their products, their risk framework, and the way they make decisions. Answering that well is what moves adoption forward."
From capability to business case
Shulman's starting point with any institutional partner is to map specific capabilities to the people who own the relevant outcomes. Faster settlement speaks to a treasury team managing liquidity and working capital. Programmability speaks to product teams looking for features they could not build on legacy rails. A shared, transparent ledger speaks to operations and compliance teams that spend heavily on reconciliation and audit.
The largest players frame it the same way. When BlackRock launched BUIDL, its head of digital assets, Robert Mitchnick, described the firm's focus as developing digital-asset solutions that "help solve real problems for our clients."
"Inside one institution, different people value different parts of the technology," Shulman says. "Treasury looks at settlement and liquidity, product looks at what they can build, compliance looks at auditability. A strong proposal connects each capability to the person who owns that outcome, instead of presenting the technology as one big idea."
Designing deals institutions can approve
Institutional adoption rarely stalls on the technology itself. It slows down in risk committees, legal reviews and procurement, where questions about custody, compliance, data and reputation have to be answered before anything goes live. Shulman's approach is to design for those reviews from the start: a tightly scoped first phase, success metrics both sides agree on upfront, clear governance and a defined path to scale.
The data backs this up. When EY-Parthenon surveyed 350 corporate and financial services executives in 2025, regulatory uncertainty was their top concern about stablecoins, cited by 73%. Interest, meanwhile, is strong: 80% of those not yet using stablecoins said they were actively exploring them.
"Institutions rarely say no to blockchain. They say 'not yet', until the risk is understood," Shulman says. "A well-designed first phase, with metrics everyone signed off on, turns 'not yet' into a decision."
This is also where her account management background shapes her view. In her experience, the first agreement only opens the relationship. The larger value comes afterwards: tracking adoption against the metrics agreed at the start, resolving issues early, and expanding into adjacent use cases once the first one has proved itself.
Choosing the partnership model
Once an institution decides to work with the technology, the next question is how. A bank or a brand can white-label a provider's product, embed it in its own app through an integration, or launch something co-branded. Each model splits the customer relationship, the economics and the regulatory responsibility differently, and Shulman argues that the choice deserves attention early in the conversation.
The industry already shows how differently those lines can be drawn. PayPal's stablecoin, PYUSD, carries PayPal's name, but it is issued by Paxos, a regulated trust company. MoonPay has since added another layer: PYUSDx, a framework that lets developers launch their own branded stablecoins backed by PYUSD. Circle and Coinbase, meanwhile, split USDC's reserve income partly according to where balances are held.
"The model decides who owns the customer, who carries the compliance work, and how revenue is shared," she says. "When both sides agree on that early, the rest of the negotiation moves much faster. When it's left vague, it usually comes back later as a problem."
Partnerships as products
Once a partnership goes live, Shulman manages it the way a strong product team manages a product: with a clear vision, a roadmap, and numbers that show exactly how it is performing. Every partnership she runs has defined goals from day one, an owner on each side, and regular reviews where the results decide the next step. This is the account management side of her work, and it is where she sees most of the long-term value being created.
"Clear goals and close tracking are what make a partnership grow," she says. "Before launch, both sides agree on what success looks like. After launch, we measure it, review it every quarter, and plan the next stage together. When both teams can see the value in the numbers, the partnership grows well beyond the first deal."
Through the cycle
Shulman has worked in digital assets through both a boom and a downturn, and she sees the cycle as one of the industry's strengths. Down markets are when the real building happens: teams ship products, strengthen their infrastructure, and lay the groundwork for partnerships. Booms are when that work reaches the market and scales.
"The best teams build when the market is quiet and sell when it's booming," she says. "The cycle also shows you very clearly who is in this industry for the long term. The companies and people who keep building through a downturn are the ones you want as partners when the next wave comes."
That long-term view is exactly what institutions look for, she argues. Banks and asset managers plan in years, and they choose partners who have shown they are here to stay.
The hybrid commercial team
All of this, she argues, calls for a different kind of commercial team. Crypto-native teams are fluent in token design, on-chain metrics, and community-led growth. Institutional sales require fluency in procurement cycles, compliance requirements, and decisions that involve many stakeholders. The companies that scale will need people who can do both.
"The strongest commercial people in this industry can discuss token design with a protocol team in the morning and a risk framework with a bank in the afternoon," she says. "That combination is still rare, and it's becoming one of the most valuable skills in the market."
Shulman works in exactly that space between the two. In practice, that means translating in both directions: helping protocol teams present what they have built in terms an institution can approve, and helping institutions see where the technology can create real value for their business.
"A big part of my job is translation," she says. "Crypto teams often have a brilliant product, and institutions have a real need for it, but they describe the same thing in completely different languages. When I connect the two, deals that look impossible start moving."
What comes next
Shulman expects blockchain to become steadily more embedded in mainstream financial products, from settlement and payments to tokenized assets and loyalty, often delivered through partners rather than standalone platforms. As that happens, she believes the measures of success will shift from token prices and user counts toward integrations, transaction volume through partners, and long-term account growth.
Shulman intends to keep working right where that shift is happening, helping the companies building the technology and the institutions adopting it grow together.
"Blockchain's advantages are real, and the next phase is about turning them into products institutions can adopt at scale," she says. "That's as much a commercial challenge as a technical one, and it's the part of the industry I find most exciting."