Beyond Mobile Banking – A List of 6 Ways to The Future
By FF Newsroom · 3 September 2015
Financial markets are in turmoil and many economists are miserable about growth prospects. But tell this to the fintech world. The outlook for mobile banking has never been brighter. Its adoption has been much faster than the internet banking that preceded it. It’s so irresistibly convenient. And there’s far more to come. Here’s six ways it could develop:
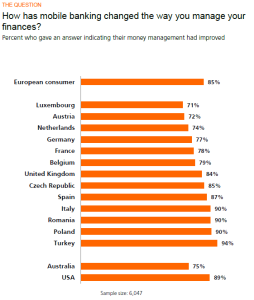 To build on this demand providers will need to develop a much deeper understanding of their users, beyond the merely financial. What are they trying to achieve in life? Their account balance and past transactions will only provide a few clues.
So providers will have to provide richer interactions with their clients to learn more about their motivations, and make intelligent inferences from the behaviour of people with similar profiles. They will also have to draw upon third-party data sources to build more complete pictures of individuals and their families, friends and social networks.
The beginnings of this trend can be seen in the market for investment products, with the launch of ‘robo-advice’ services. These offer portfolio-management tools, with automated advice based on data users provide, such as online risk-appetite evaluations. For example, younger, risk-tolerant investors will typically be advised to put a bigger proportion of their portfolios into equities, for example.
For providers and users alike, the mutual cost savings on relatively large investment transactions make them an attractive place for robo-advice to start. But there is scope for the trend to extend into the full range of financial decisions, even to mundane daily shopping transactions. Ever more efficient systems are commoditising the payments business, so the search is on, by banks and fintechs alike, for added value services around the payments business.
Here the big prize for banks is to do more than merely executing the payment. What if they could use their knowledge and data to make help you make a better choice?
Big transactions, like buying homes or cars, are months, if not years, in the planning. Right now, banks are generally only involved at, or near, the moment of payment. But with their transactions data and expertise, banks could step in to help users search, building on the experiences of millions of other customers.
Even with smaller transactions banks could play a more active role in providing tips and tools to help, given their role at the heart of the payments system. Indeed, they could embed themselves in the whole transaction journey of searching, buying and, in some cases, use (think of feedback and reviews on purchases). As a result, they would be involved not just in the ‘how’ to buy, but the ‘why’ (“do I need this?”), ‘what’ (“which product should I buy?”), ‘when’ (“should I wait?”) and ‘where’ (“who’s offering the best deal?”). The obvious question is: would users want this? The short answer is yes, so long as they found it useful. That usefulness will be enhanced by the other emerging fintech trends.
- Advice
 To build on this demand providers will need to develop a much deeper understanding of their users, beyond the merely financial. What are they trying to achieve in life? Their account balance and past transactions will only provide a few clues.
So providers will have to provide richer interactions with their clients to learn more about their motivations, and make intelligent inferences from the behaviour of people with similar profiles. They will also have to draw upon third-party data sources to build more complete pictures of individuals and their families, friends and social networks.
The beginnings of this trend can be seen in the market for investment products, with the launch of ‘robo-advice’ services. These offer portfolio-management tools, with automated advice based on data users provide, such as online risk-appetite evaluations. For example, younger, risk-tolerant investors will typically be advised to put a bigger proportion of their portfolios into equities, for example.
For providers and users alike, the mutual cost savings on relatively large investment transactions make them an attractive place for robo-advice to start. But there is scope for the trend to extend into the full range of financial decisions, even to mundane daily shopping transactions. Ever more efficient systems are commoditising the payments business, so the search is on, by banks and fintechs alike, for added value services around the payments business.
Here the big prize for banks is to do more than merely executing the payment. What if they could use their knowledge and data to make help you make a better choice?
Big transactions, like buying homes or cars, are months, if not years, in the planning. Right now, banks are generally only involved at, or near, the moment of payment. But with their transactions data and expertise, banks could step in to help users search, building on the experiences of millions of other customers.
Even with smaller transactions banks could play a more active role in providing tips and tools to help, given their role at the heart of the payments system. Indeed, they could embed themselves in the whole transaction journey of searching, buying and, in some cases, use (think of feedback and reviews on purchases). As a result, they would be involved not just in the ‘how’ to buy, but the ‘why’ (“do I need this?”), ‘what’ (“which product should I buy?”), ‘when’ (“should I wait?”) and ‘where’ (“who’s offering the best deal?”). The obvious question is: would users want this? The short answer is yes, so long as they found it useful. That usefulness will be enhanced by the other emerging fintech trends.
- Access
- Affective
- Associative
- Agile
- Ambient